Are Stablecoins the Future of Everyday Money—or Just a Crypto Fantasy?
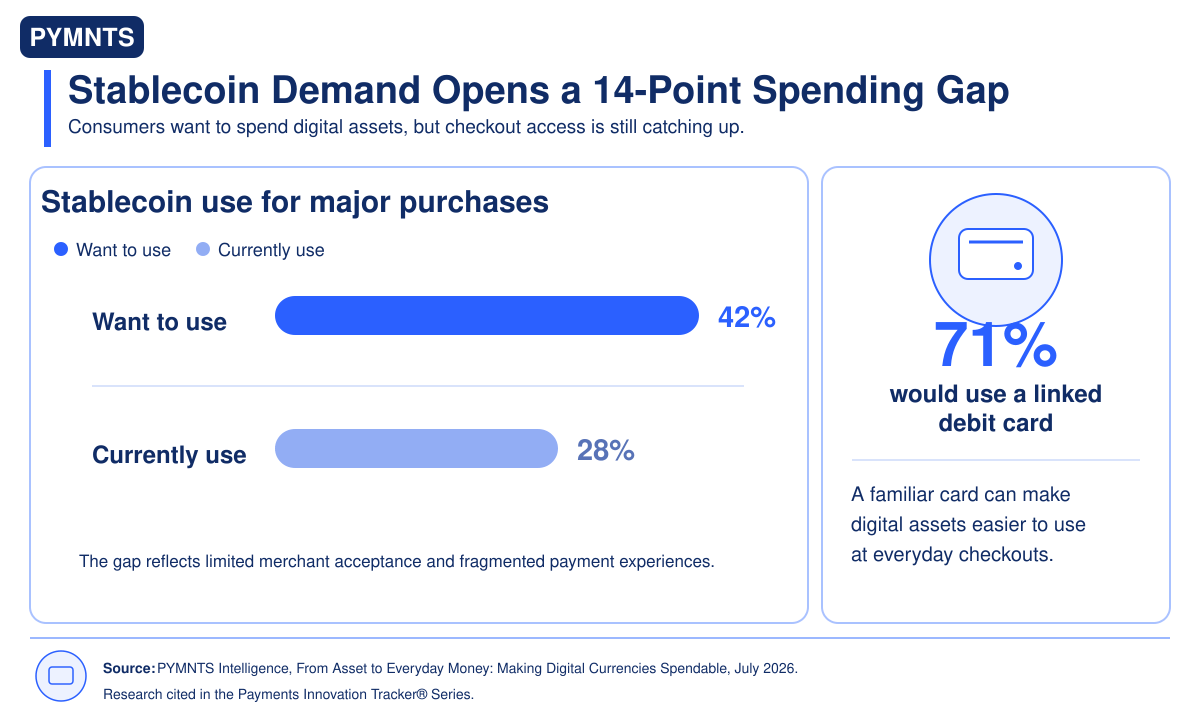
Let me ask you this: If 71% of stablecoin holders say they’d use a debit card to spend their digital assets, does that mean we’re on the brink of a financial revolution—or are we just witnessing another tech bubble desperate for mainstream adoption? The PYMNTS report on stablecoin adoption isn’t just about numbers; it’s a mirror reflecting our collective obsession with reinventing money in the digital age. But here’s the uncomfortable truth: The gap between wanting to use crypto and actually doing it reveals a deeper disconnect between innovation and reality.
The Illusion of Demand: Why Wanting Isn’t the Same as Spending
The 14-point gap between stablecoin holders who want to use their assets for major purchases (42%) and those who actually do (28%) isn’t a failure of consumer interest—it’s a failure of imagination. Personally, I think the crypto industry has spent too long trying to force users into its vision of the future instead of meeting them where they are. People don’t want another app to juggle; they want their existing tools—banking apps, debit cards, payment networks—to magically handle digital assets without requiring a PhD in blockchain. The real story here isn’t about crypto adoption; it’s about the stubborn persistence of convenience.
What many people don’t realize is that this gap mirrors the early days of mobile payments. Remember when Apple Pay was supposed to revolutionize wallets? Adoption only took off when it was embedded seamlessly into devices we already owned. Stablecoins face the same hurdle: They’re asking consumers to layer complexity onto simplicity, not replace it.
Bridging the Gap with Familiar Tools: The Debit Card Gambit
Let’s unpack that 71% figure. On the surface, it’s a vote of confidence in debit cards as crypto onramps. But dig deeper, and you’ll find a fascinating paradox: The very technology designed to disrupt traditional finance is now begging for validation through 20th-century infrastructure. In my opinion, this isn’t hypocrisy—it’s pragmatism. Crypto holders aren’t rejecting innovation; they’re demanding interoperability. They want their digital dollars to work at Walmart, not just on obscure exchanges.
A detail that stands out here is the analogy to “putting new fuel through the same pump.” But this metaphor misses a crucial difference: Gasoline doesn’t care which pump it flows through. Money, however, carries cultural and psychological baggage. For every person excited about instant crypto conversions, there’s a merchant terrified of price volatility or fraud. This raises a deeper question: Are we solving for user convenience or institutional inertia?
The Trust Paradox: Why Banks Might Save Crypto From Itself
Here’s a twist: 77% of consumers prefer opening stablecoin wallets through existing banking or FinTech apps. What this really suggests is that crypto’s biggest obstacle isn’t technology—it’s trust. Despite the anti-establishment roots of blockchain, users are fleeing to the very institutions they once sought to overthrow. From my perspective, this isn’t a defeat; it’s a maturation. People don’t need another frontier of financial risk—they need guardrails that make experimentation feel safe.
Compare this to the early days of online banking, which thrived not because it was revolutionary, but because it piggybacked on existing trust in banks. The irony? Crypto’s path to mainstream adoption may require embracing the boring stability of traditional finance rather than rejecting it.
The Bigger Picture: Why Stablecoins Matter Beyond the Checkout Lane
While the report highlights stalled progress in retail adoption, it also reveals a quiet revolution in cross-border business payments. Stablecoins solving “practical problems” for global transactions—that’s where the real action is. If you take a step back and think about it, this mirrors the historical adoption of the U.S. dollar itself: First dominating international trade, later becoming a household currency. Maybe stablecoins are following the same playbook, just in reverse.
But let’s not ignore the elephants in the room: 45% of users cite transaction costs, 43% volatility, and 36% fraud concerns. These aren’t temporary glitches; they’re structural challenges. The crypto industry’s tendency to dismiss these issues as “early adoption problems” risks creating a self-fulfilling prophecy of stagnation.
Final Thoughts: The Curious Case of the Missing Revolution
So where does this leave us? With a fascinating contradiction: Record growth in crypto card spending ($18 billion annualized!) alongside stubborn resistance to everyday use. My take? This isn’t a paradox—it’s a signpost. The future of money isn’t about choosing between crypto and fiat; it’s about blending them so seamlessly that the distinction disappears. But until merchants can accept stablecoins without fearing overnight devaluation, and until Grandma can buy groceries with her crypto without a tech-savvy grandkid nearby, the revolution will remain… pending.
What this moment demands isn’t more whitepapers or wild price swings. It’s the boring, unglamorous work of building bridges between the blockchain and the lunch counter. Because money only changes the world when it stops trying to prove it’s innovative—and just works.